
Your guide to
Business Insurance in Texas
Every business carries different risks, from customer injuries to damaged equipment and company vehicles. Our agency helps you understand the main types of business coverage and which ones may fit the way you work.
What it covers
Types of business insurance
Many businesses combine several types of coverage. Explore each one to learn what it is generally designed to protect.
-
Business owners policy (BOP)
Bundles property and general liability coverage into one policy, often designed for small and midsize businesses.
Learn more -
General liability
Helps protect your business if it is held responsible for injuries to others or damage to their property.
Learn more -
Commercial property
Helps cover your business building, equipment, inventory and furnishings after a covered loss, such as a fire.
Learn more -
Commercial auto
Helps protect the cars, trucks and vans your business uses for work, with liability and physical damage options.
Learn more -
Workers' compensation
Can help pay medical costs and lost wages when an employee is hurt or becomes ill because of the job.
Learn more -
Professional liability (E&O)
Helps protect you when a client claims a mistake or oversight in your professional services caused a financial loss.
Learn more -
Cyber insurance
Can help with costs after a data breach, ransomware or other cyber incident, depending on the policy.
Learn more -
Surety bonds
Back a promise your business makes to a customer, project owner or government agency, such as finishing a job or following license rules.
Learn more -
Contractors
Coverage for contractors and the trades, often combining liability, tools and equipment, vehicles and protection for your crew.
Learn more
Why it matters
Build coverage around how your business really works
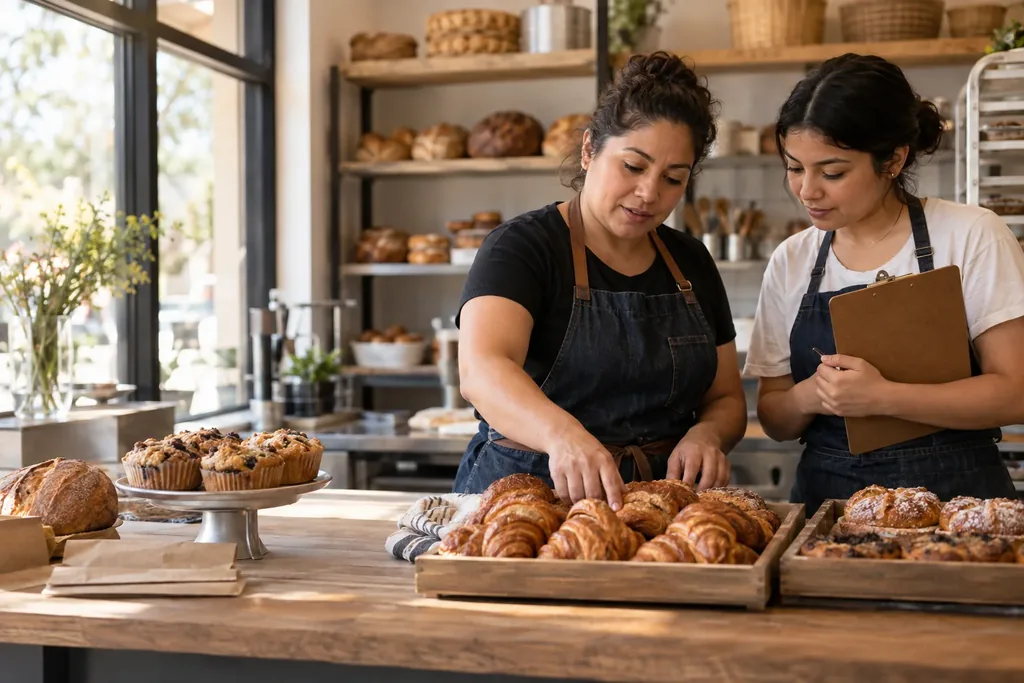
A bakery, an online shop and a roofing crew face very different risks. The mix of coverage that fits depends on your property, your vehicles, your employees, the contracts you sign and the kind of work you do.
Many small businesses begin with a business owners policy or general liability, then add coverage as they grow. We can help you compare options in English or Spanish and review your coverage when your business changes.
Leases and client contracts often include insurance requirements, so it helps to review them before you sign.
Get ready
Details that help our team review your business
- What your business does
- Where you operate
- Number of employees
- Estimated annual payroll
- Vehicles used for work
- Property you own or lease
Documents worth having on hand
- Current policies
- Contracts with insurance requirements
- Commercial lease
- Past claims information
- Driver list
Answers
Business insurance questions
Straight answers to common questions. If yours is not here, call or text our agency.
It depends on what you do, whether you have employees or vehicles, and what your leases and contracts require. Many small businesses start with a BOP or general liability, then review other coverage.
Requirements depend on the coverage and your situation. For example, Texas generally requires liability coverage for vehicles, while leases, contracts and some licenses may require other coverage.
Yes. We can go over your current policies with you in English or Spanish and help you understand what they cover and where there may be gaps.
Request a quote
Tell us what you need
Your name, a number that reaches you, an email, and a few quick questions about the coverage you pick. Our team reviews it and calls you back.
Rather just talk? (281) 875-8484People who read this also looked at
Next step
Let’s review your needs to find the coverage that fits you.
Request a quote online, or call or text our agency. If your current policy already fits, we will tell you that too.